CMHC-insured financing structured for the long term, and one team in your corner from application to maturity.
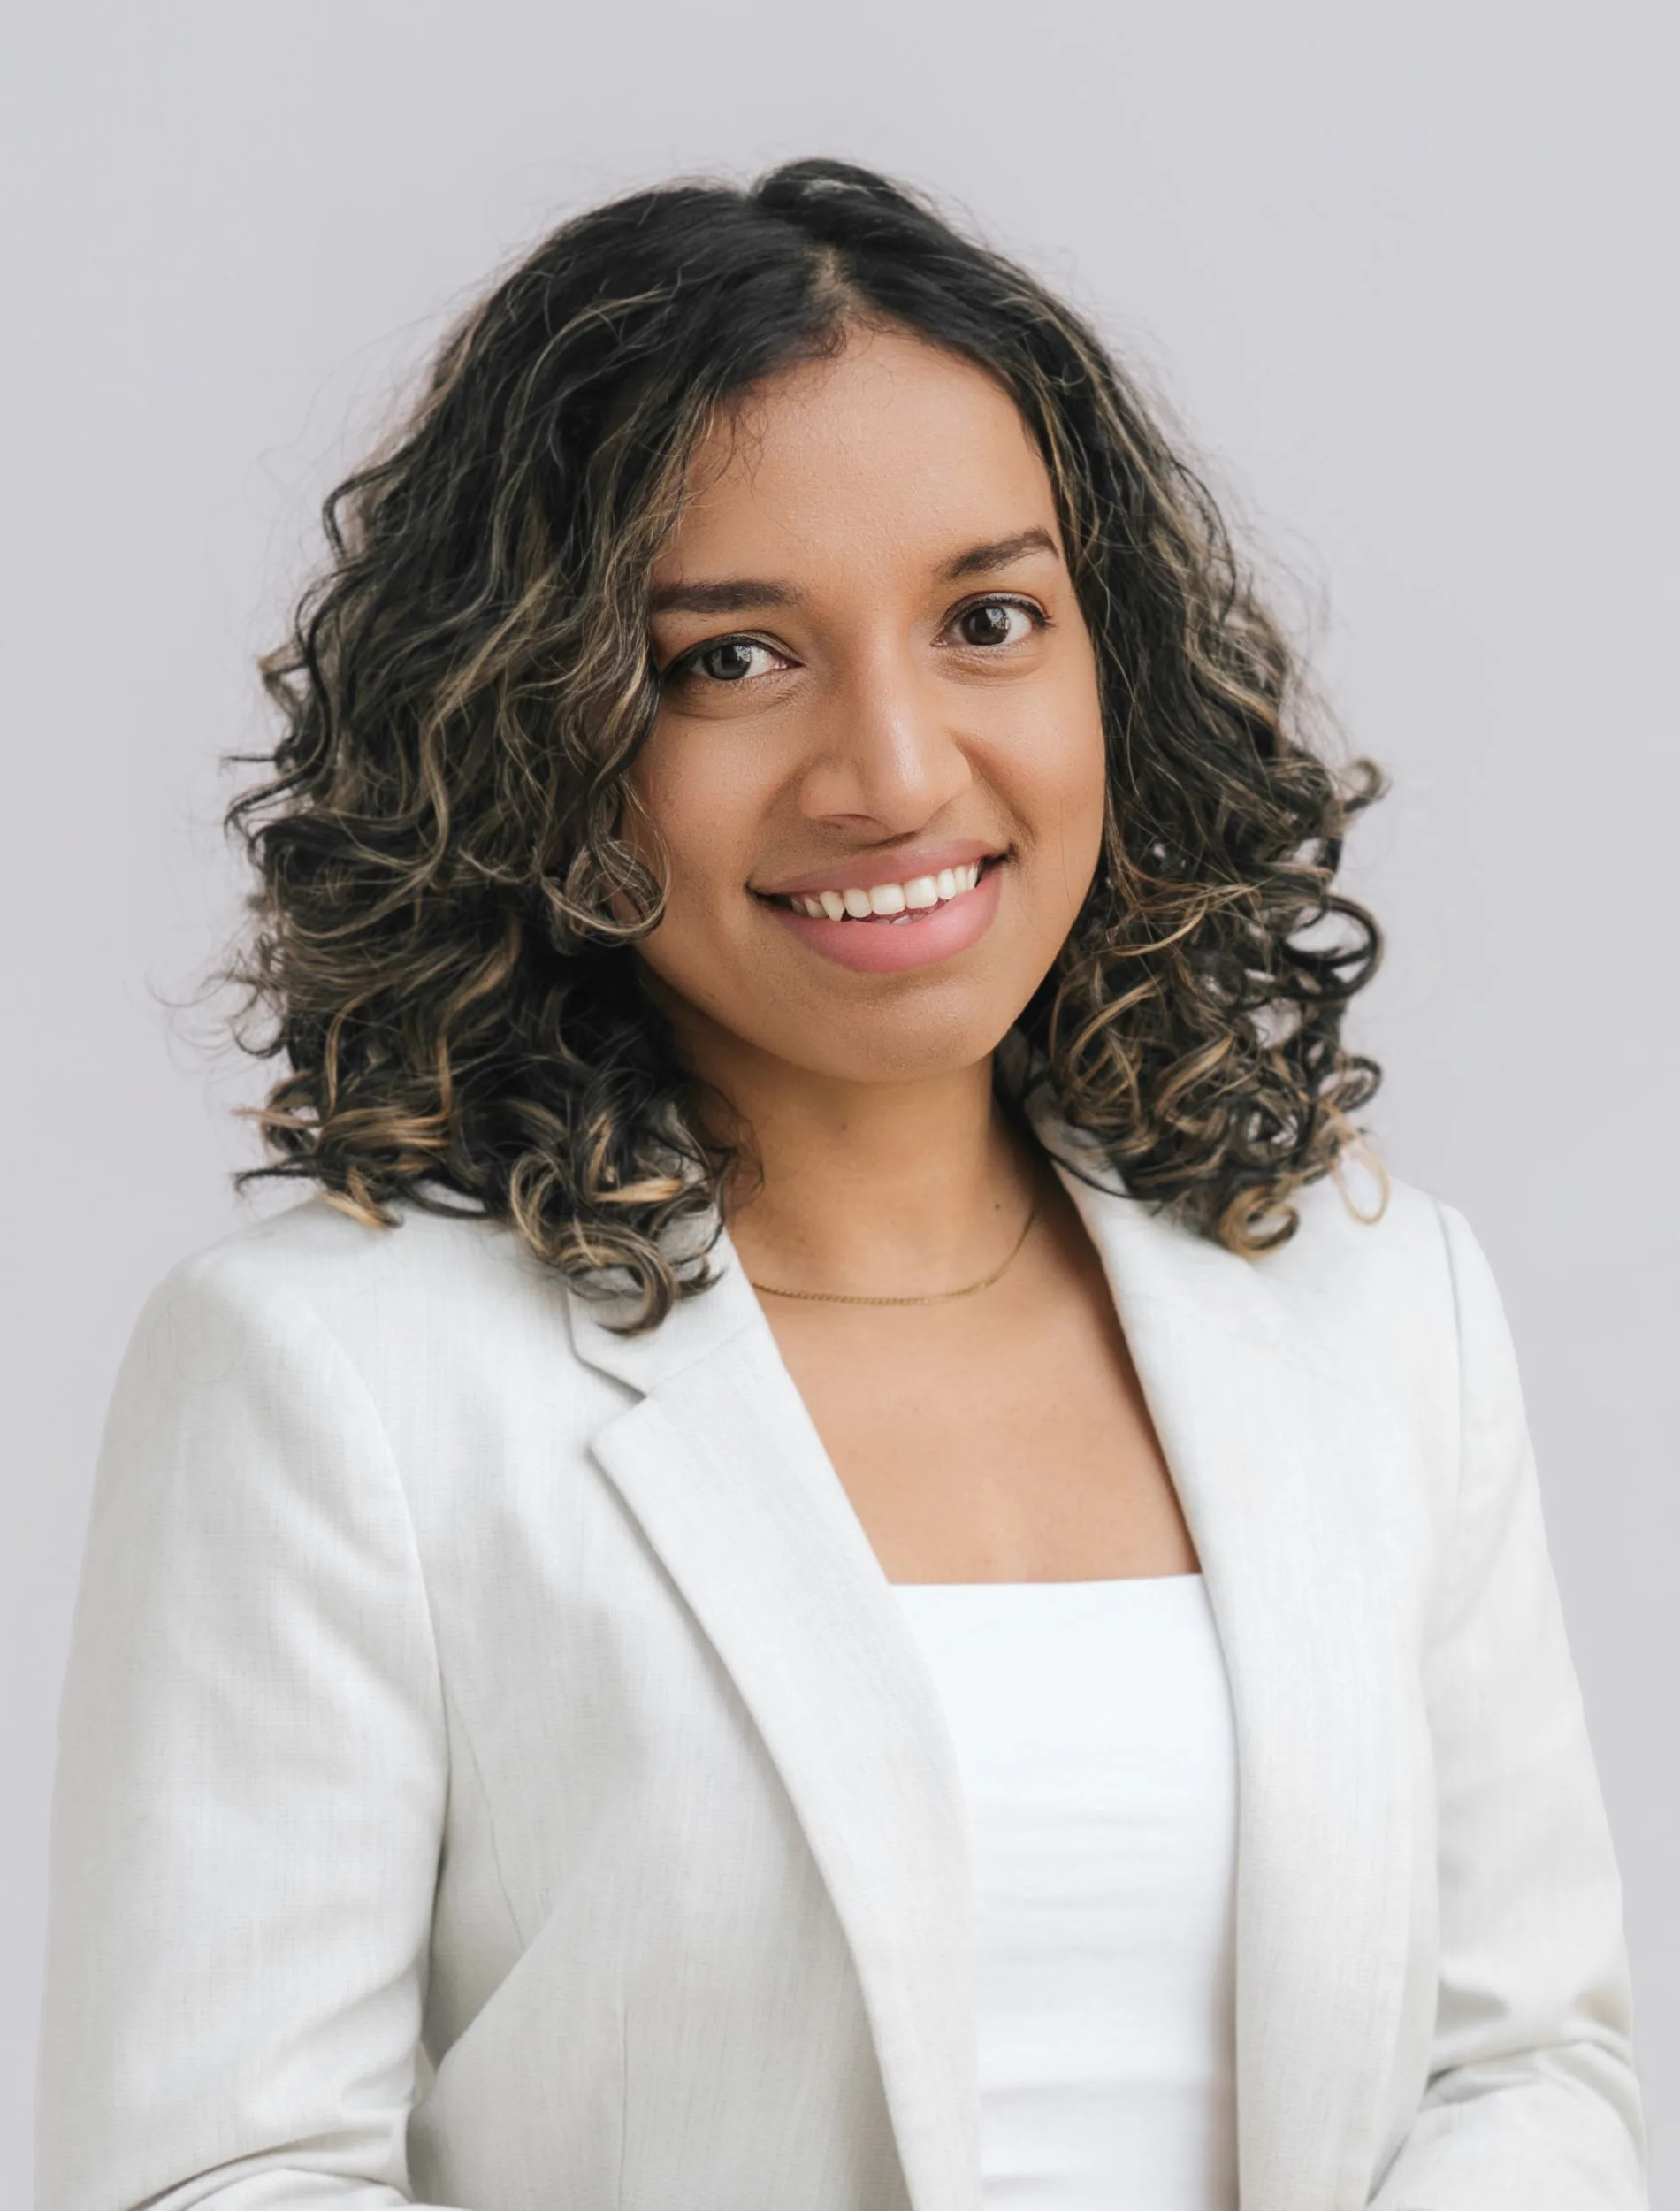
Maitri Shetty
Vice President, Insured Lending
Since 2006
Lending on real estate
$2.5 billion+
In real estate loans funded
Standard and MLI Select
Insured term options
Alta., B.C., Sask. and Ont.
Where we lend
Why KV Capital?
An established, CMHC-approved lender
We’ve lent on real estate since 2006 and underwritten private loans since 2009, with more than $2.5 billion in real estate loans funded.
One team, from application to maturity
We submit your application to CMHC and support you all the way to the maturity of your loan, as we do for every loan we make.
Built for complex deals
CMHC’s parameters are fixed. How we structure within them is where two decades of lending experience shows. Our real estate equity and building-products businesses also give us a close read on construction and operating costs.
From bridge to long-term debt
If your building is on a KV bridge or construction loan today, we already know the sponsor and the asset, which makes the move to insured term financing simpler.
Rooted in Western Canada
Offices in Edmonton, Calgary and Toronto, long relationships across Alberta and a fast-growing book in British Columbia.
Our CMHC track record
Before becoming a CMHC-approved lender, KV Capital arranged CMHC-insured financing for multifamily projects across Western Canada.
Arranged financing for a purpose-built mixed-use rental project in Edmonton with 163 residential units and 10 commercial spaces.
Arranged a $25.8-million CMHC-insured construction loan at 95 per cent loan-to-cost for a 74-unit purpose-built rental project in Cochrane, Alta.
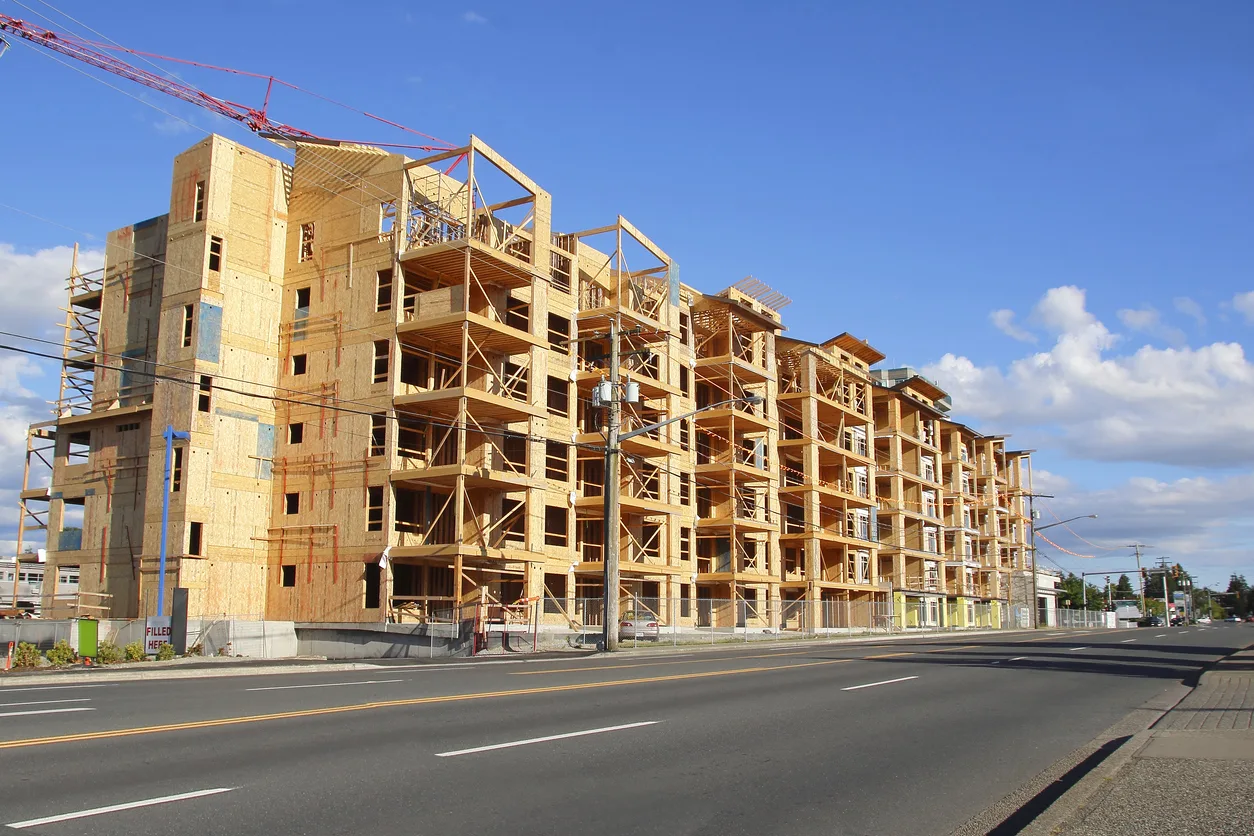
Arranged an $11-million mezzanine loan behind a CMHC MLI Select construction loan for a 193-unit multifamily rental project in the Okanagan.
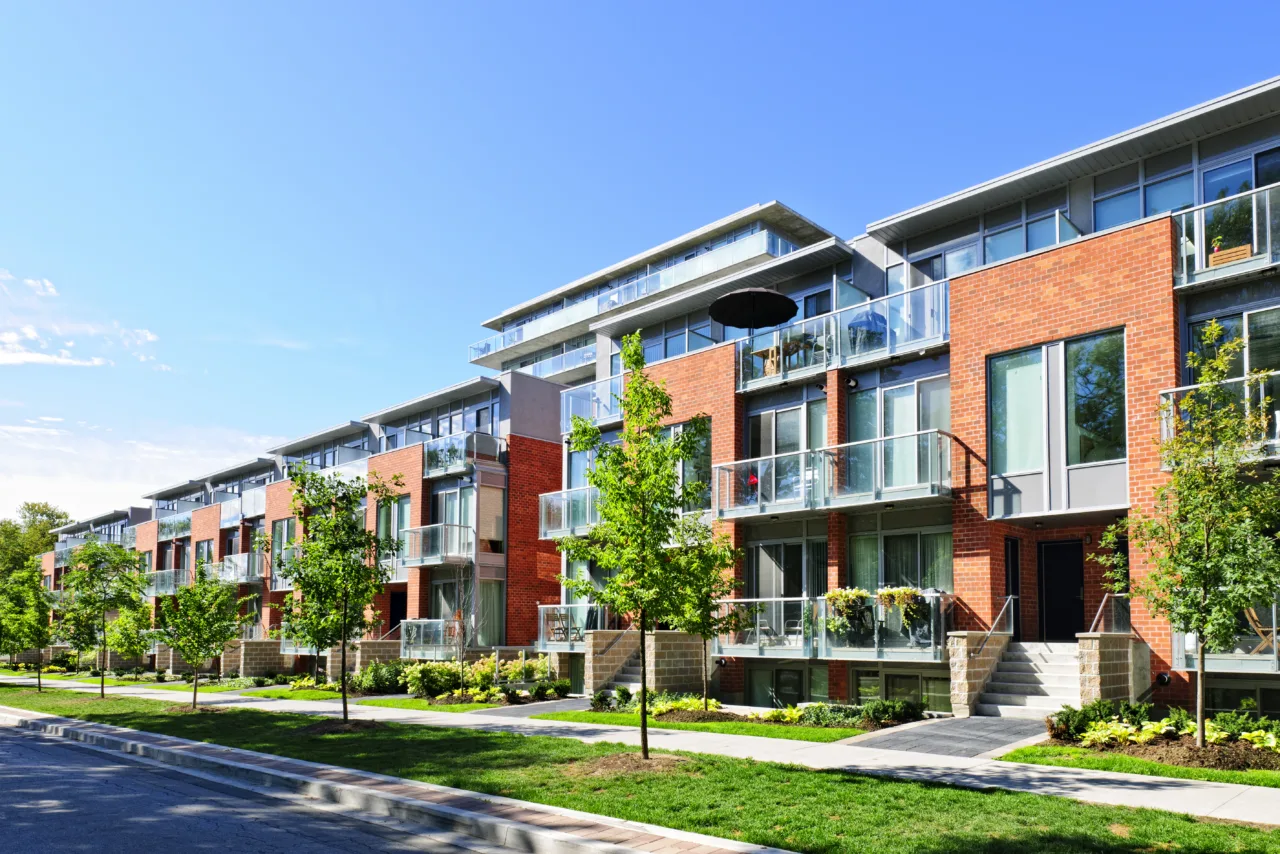
Arranged $3.5 million in CMHC construction financing for an eight-unit multifamily project in West Hillhurst, Calgary.
About CMHC-insured financing
Canada Mortgage and Housing Corp. (CMHC) insures mortgages on rental buildings with five or more units. Because the loan is insured, lenders can offer terms conventional financing rarely matches. In exchange, you pay a one-time insurance premium, usually added to the loan.
The common hurdles are preparing an application CMHC will approve and choosing the right program for your building. As a CMHC-approved lender, we handle both: we advise on structure, prepare and submit your application to CMHC, and manage your file through to funding.
| Conventional | CMHC-insured | |
|---|---|---|
| Amortization | Typically 25 to 30 years | Up to 40 years, or up to 50 with MLI Select |
| Leverage | Typically 65% to 75% | Up to 85%, or up to 95% with MLI Select |
| Debt coverage | Typically 1.20 to 1.30 or higher | From 1.10 on residential space |
| Rates | Market-driven | Priced off Canada Mortgage Bond yields |
Figures are subject to change. Please refer to the most recent CMHC advice for current requirements.
Key benefits of CMHC-insured financing
Lower interest rates
Insured pricing reduces your borrowing cost and monthly payments, freeing up capital.
Extended amortization
Amortization up to 40 years, or up to 50 years with MLI Select.
Leverage up to 95 per cent
Finance up to 85 per cent of your building’s value, or up to 95 per cent with MLI Select.
Premium savings on insured refinances
Refinancing an existing CMHC-insured loan? You may qualify for a credit on the premium you already paid.
Figures are subject to change. Please refer to the most recent CMHC advice for current requirements.
Insured term mortgages
Long-term CMHC-insured financing for stabilized standard rental and mixed-use buildings. Use it to refinance or renew a loan maturing with another lender, take equity out of a stabilized building, acquire an existing property, fund renovations as part of a refinance, or move a completed rental project off bridge or construction financing onto long-term insured debt.
Two ways to structure your term mortgage
Standard
Up to 85 per cent loan-to-value and amortization up to 40 years.
MLI Select
Commit to affordability, energy efficiency or accessibility and unlock up to 95 per cent loan-to-value, amortization up to 50 years and premium discounts of 10 to 30 per cent.
Figures are subject to change. Please refer to the most recent CMHC advice for current requirements. All loans are subject to CMHC and KV Capital approval.
Eligibility criteria
Specific criteria for borrowers and properties include:
Criteria are subject to change. Please refer to the most recent CMHC advice for current requirements.
What to expect
A clear process, from preparation through to maturity.
1. Preparation
KV Capital underwrites the file, prepares documentation and conducts an independent review before submission.
2. CMHC review
CMHC reviews the application and issues its approval. KV Capital manages the CMHC relationship throughout.
3. Funding
The loan funds. KV Capital co-ordinates closing with you and your legal counsel.
4. Post-funding support
We support you through the life of your loan, and when your term ends you can renew with KV Capital.
Frequently asked questions
Answers to the questions we hear most from multifamily owners about CMHC-insured financing.
What is a CMHC-insured multifamily mortgage?
It’s a mortgage on a rental building with five or more units, insured against default by Canada Mortgage and Housing Corp. Because the loan is insured, lenders can offer longer amortizations, higher leverage and lower debt coverage requirements than conventional financing.
What does insurance cost?
CMHC charges a one-time premium based on your loan-to-value (LTV) ratio, typically added to the loan. For a standard refinance or purchase, it ranges from 2.6 per cent of the loan at 65 per cent LTV to 5.35 per cent at 85 per cent LTV, with surcharges for amortizations beyond 25 years. MLI Select can reduce the premium by 10 to 30 per cent.
How does it compare with conventional financing?
Insured financing usually delivers a lower payment and higher proceeds on the same building, thanks to longer amortization and higher leverage. The premium is the trade-off. We’ll model both options on your building so you can compare total cost.
What is MLI Select?
MLI Select is a CMHC option that rewards commitments to affordability, energy efficiency or accessibility with better terms. At KV Capital, it’s available within our insured term mortgages.
Does my building qualify for MLI Select?
You need at least 50 points under CMHC’s MLI Select scoring system, earned through commitments to affordability, energy efficiency or accessibility. For an existing building, the most common routes are keeping 40 per cent or more of units at rents within 30 per cent of local median renter income for 10 years, or reducing energy use and emissions by 15 to 40 per cent. We can run a quick points check with you.
What does it mean that KV Capital is a CMHC-approved lender?
We submit your application to CMHC ourselves and manage your file from application through to funding. You work with one team the whole way. KV Capital has lent on real estate since 2006, with more than $2.5 billion in loans funded.
My building is on a KV bridge or construction loan. Can I move to CMHC-insured financing with you?
Often, yes. Once the building is complete and the rents are stabilized, insured term financing can replace short-term debt. Because we already know your project, the move is usually simpler. Talk to your KV lending contact well before your current loan matures.
My loan is maturing with another lender. Can I move it to KV?
Yes. Refinancing or renewing a loan from another lender is one of the most common reasons operators come to us. If your current loan is CMHC-insured, you may also qualify for a credit on the premium you already paid.
Where do you lend?
Alberta, British Columbia, Saskatchewan and Ontario.
What do I need to get started?
A current rent roll, three years of operating statements, your current mortgage details and a personal or corporate net worth statement. Your KV contact will confirm the full list with your term sheet.
Figures and program details on this page are summaries for general information only and are subject to change. Please refer to the most recent CMHC advice for current requirements. All loans are subject to CMHC and KV Capital approval.
Meet your CMHC team
Broker partnerships
We partner with established mortgage brokers on CMHC-insured financing for multifamily and mixed-use properties, with a dedicated contact on our insured lending team from application through closing.
Multifamily insights
Our upcoming Desk note will cover rental market trends, MLI Select in practice and the financing outlook for multifamily owners. Subscribe below to get the first issue in your inbox.

Benefit from our deep understanding of CMHC-insured financing.
Tell us about your building and your timing. We'll come back with how insured financing could work for you.
All loans are subject to CMHC and KV Capital approval. Terms and program details are subject to change; please refer to the most recent CMHC advice.